
Till: Debit Card for Kids
- Rating
- 4.5
- Downloads
- 100.00K
- Content Rating
- Everyone
Till: Debit Card for Kids - Screenshots
Pros
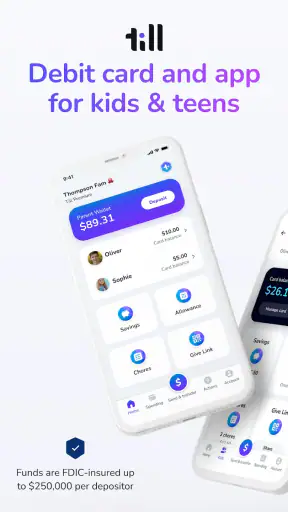
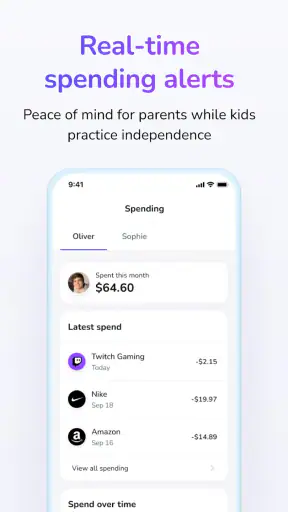
- Parents can set spending limits and monitor transactions in real time.
- Kids can learn budgeting through controlled
- everyday card spending.
- Cards are designed for children and can be managed from a parent account.
- Transaction alerts help parents quickly spot unexpected purchases.
- Useful for introducing cashless payments without giving full bank access.
Cons
- Availability and features may depend on the user's country and age requirements.
- Some advanced controls or features may require a paid subscription.
- Younger children may still need guidance to understand digital spending.
- A lost physical card can temporarily interrupt access to funds.
- Requires a compatible smartphone and reliable internet for account management.
Till: Debit Card for Kids - Description
- App Name
- Till: Debit Card for Kids
- Package Name
- io.tillfinancial.till
- Developer
- Till Financial
- Category
- Finance
- Last Updated
- Apr 27, 2022
- Version
- 162.41.0
Managing a child’s first spending decisions is a very different problem from choosing another banking app for yourself. I looked at Till: Debit Card for Kids as a household tool rather than simply a finance download, and that distinction matters. It is designed around a debit card and an app for helping kids and teens become more thoughtful spenders, so its value appears when an adult and a young person need to stay connected to everyday money without treating the child like a full independent banking customer.
In my experience, the most useful way to judge Till is to imagine a normal family routine: a teenager is going to school, meeting friends, or buying something small, while a parent wants spending to happen through a clear, agreed channel instead of handing over cash every time. The app can fit that situation well. It is less convincing for someone who only wants a basic personal budget, a conventional adult checking account, or a general-purpose payment wallet.
How Till fits into a shared household routine
The strongest use case is shared responsibility. A young person gets a practical way to make purchases, while the adult remains part of the financial conversation. That can turn abstract lessons about saving and spending into decisions that happen during an ordinary week. Buying lunch, paying for a small activity, or deciding whether an item is worth the money all become opportunities to practice judgment.
I would not describe this as a miniature version of an adult banking app. The point is not to give a child every financial tool at once. The point is to create a more manageable first step. That makes the app particularly relevant for families who want to move beyond cash but are not ready to treat a young person’s spending as completely separate from the household.
A realistic scenario might look like this: a parent and teenager agree on how money will be used before the teenager leaves for the day. The teenager then uses the debit card for an ordinary purchase and can think about the balance afterward instead of asking for cash at each stop. Later, the two can discuss whether the spending matched the plan. The important benefit is not just the transaction; it is the repeatable conversation around the transaction.
That shared-device angle also deserves attention. Some families may review money together on one phone, while others may use separate devices at different moments. I would approach the app with clear household habits from the beginning: decide who checks the account, who discusses purchases, and where the young person can ask questions. The app should support that routine, but it cannot replace an agreement between the people using it.
There is a subtle trade-off here. A shared financial tool can make money feel less secretive and more teachable, but it can also create friction if everyone expects the same level of access or visibility. Before setting it up, I would talk through boundaries in plain language. A child should know which spending decisions are theirs, which decisions require an adult conversation, and what to do if the card does not work or a purchase looks unfamiliar.
What the setup means for household boundaries
Setting up a youth-focused money product is not the same as downloading a simple expense tracker. The adult should treat the first setup session as part of the lesson. Rather than rushing through screens, I would sit with the child and explain the purpose of the card, how available money should be treated, and why checking a balance before spending is useful.
This is also where families should avoid making assumptions based on age alone. A responsible older teen may need more room to make decisions than a younger child, but the app itself does not remove the need for household rules. Till is best used when the family decides how much independence is appropriate and then reviews that arrangement as the child gains experience.
One practical tip is to start with a small number of predictable spending situations. For example, use the card for agreed everyday purchases before relying on it for every possible expense. This gives the young person a chance to learn the rhythm of checking money, paying, and reflecting afterward. It also gives the adult a chance to notice confusion early, when correcting the habit is easier.
Another useful boundary is separating convenience from permission. A child may have a card for approved spending, but that does not automatically mean every purchase is acceptable. I would make that distinction explicit. “You can use the card” and “you can buy anything” are not the same message, and the app works better when the family does not leave that difference vague.
Households should also consider the practical side of a shared device. If a parent and child sometimes look at the app together, avoid treating the phone as a private space during those moments and avoid leaving financial screens open where another person could casually use them. This is not a criticism of Till specifically; it is simply sensible behavior for any app connected to money.
Coordinating without turning every purchase into an argument
The best household workflow is light enough to maintain. If an adult checks every small purchase immediately or turns each transaction into an interrogation, the child may learn to fear mistakes rather than understand spending. I would use Till as a prompt for short, regular conversations instead: What was the purchase? Was it expected? Would you make the same choice again?
That approach helps the card serve an educational purpose without making the app feel like a constant surveillance tool. The young person still gets practice making choices, while the adult can provide context when something is unclear. It also makes it easier to distinguish an honest mistake from a repeated pattern that needs a new household rule.
Coordination matters especially when more than one adult is involved. Parents, guardians, or other caregivers should agree on the same basic expectations before the child starts using the card. If one adult treats the money as flexible and another treats it as tightly restricted, the resulting confusion is likely to be blamed on the app even though the real problem is inconsistent communication.
I would recommend agreeing on three simple questions: what kinds of purchases are routine, when should the child ask first, and how will the family respond when money is spent differently than expected? These questions are more useful than creating a long list of rules that nobody remembers. Till can be part of the process, but the household still supplies the decision-making framework.
There is also a useful distinction between teaching budgeting and teaching restraint. A child may understand how much money is available and still choose to spend it quickly. That is not necessarily a technical failure. It may be the exact lesson the family needs to discuss. The app gives the spending experience a concrete form, but the adult has to help the child connect today’s purchase with tomorrow’s options.
For families with siblings, coordination can become more complicated. I would avoid comparing children’s spending in a way that turns the card into a competition. Different ages, needs, and levels of independence can justify different expectations. A shared household system should create clarity, not pressure to make every child use money in exactly the same way.
Age, trust, and the right level of independence
Till has an Everyone content rating, which makes the app approachable from a content perspective, but that should not be confused with a promise that every child is ready to manage a debit card. Readiness depends on whether the young person can understand basic spending limits, keep track of a card, ask for help, and accept that money is finite.
For a younger child, the adult may need to be closely involved in every stage. For a teenager, the more valuable role may be coaching: setting expectations, allowing ordinary decisions, and reviewing what happened afterward. In both cases, trust should grow from observed behavior rather than from age as a number.
One of the app’s more interesting strengths is that it places financial learning in situations where mistakes can be discussed. A child who spends impulsively may discover the consequence quickly. A child who plans ahead may experience the benefit of keeping money available. Those lessons are more memorable than a lecture, but they only work if the household treats mistakes as information rather than as a reason to abandon the system immediately.
At the same time, I would not use Till as a substitute for teaching cash awareness, privacy, or basic fraud caution. A child should know not to share card details casually, should understand that a strange transaction needs adult attention, and should know what to do if the card is lost. The app may make money easier to organize, but it does not make financial judgment automatic.
Trust also has an emotional side. Some children will appreciate having a card because it makes them feel more independent. Others may feel anxious if every purchase becomes a report to an adult. Before introducing it, I would explain why the family is using it and what kind of support the child can expect. The aim should be guided independence, not simply control through technology.
Where it stands beside ordinary alternatives
The usual alternative for a younger person is cash. Cash is immediate and easy to understand, and it does not require a phone or an app. It can also be awkward when a child needs money unexpectedly, and it offers less convenience for families trying to establish a consistent digital spending routine. Till is more suitable when the household wants a debit-card experience connected to an app rather than an envelope of notes.
A basic budgeting app is another comparison. That kind of tool may be excellent for recording expenses, but recording what happened is different from giving a young person a structured way to participate in spending. Till is more focused on the relationship between the child, the card, and the adult conversation. If your goal is only to categorize your own expenses, a standard budget tracker may be simpler.
An adult bank account can provide broader financial functionality, but that breadth may be unnecessary or even confusing for a first spending experience. Till’s appeal is its narrower purpose: helping kids and teens build habits with adult involvement. The trade-off is that a family seeking full adult banking features, complex financial planning, or a single account for every household need may prefer a conventional financial institution instead.
It is also worth remembering that the app is free to install, while in-app purchases range from about eight dollars to about eighty dollars per item. I would check the current purchase choices carefully before treating the service as cost-free in practice. That pricing detail does not automatically make Till poor value, but it does mean families should understand what they are choosing and whether the available arrangement fits their budget.
The developer is Till Financial, and the app has reached over one hundred thousand installs with an average rating of about four and a half stars from around two thousand ratings. Those figures suggest that the product has found an audience, but they should not replace a personal check of fit. A positive average cannot tell you whether the household workflow will suit your child’s temperament or your family’s communication style.
Everyday friction I would consider first
The biggest limitation is not a missing button; it is the possibility of unclear expectations. If the adult assumes the app will teach responsibility automatically, disappointment is likely. A child still needs explanations, reminders, and room to ask questions. The product can make those conversations easier to anchor, but it cannot have them for you.
There can also be friction when a young person wants immediate independence and the adult wants constant reassurance. That tension exists with any youth debit-card product. Till makes sense when both sides accept a gradual process. It is a poor fit if the child is expected to manage everything alone from the start or if the adult is unwilling to let the child make any meaningful decisions.
Shared-device use adds another practical concern. Families should establish who is looking at the account and when, especially if several people use the same phone or tablet. I would not rely on casual handoffs for anything involving money. A short household routine—open the app deliberately, review the relevant information, close it afterward—reduces confusion and keeps the financial discussion intentional.
Version updates are another reason to keep expectations realistic. The current version is 162.41.0, and the app supports Android 7.0 or later. That makes it accessible on many older Android phones, but compatibility alone does not guarantee that an older device will feel pleasant to use. If the household phone is slow, shared, or often unavailable, the convenience of an app-based card may be reduced.
I would also skip Till if the real goal is to hide money management from a child rather than teach it. A youth finance tool works best when the young person understands the basic rules and participates in the process. Likewise, if you need a sophisticated adult banking setup, a general finance app or traditional bank account may be a better match than a product built around guided spending for kids and teens.
My household verdict
After looking at how it fits into real family routines, I see Till as a focused bridge between cash allowance and adult financial independence. Its best quality is not that it puts a debit card in a child’s hand; it is that it gives the household a concrete way to discuss choices, limits, and consequences while the child is still learning.
I would recommend it to a parent or guardian who wants a shared, age-aware starting point and is willing to stay involved. Begin with clear rules, use ordinary purchases as practice, and review decisions without turning every mistake into a punishment. That workflow gives the app its best chance to build confidence rather than dependence.
I would be more cautious for families that want a completely hands-off solution, need advanced adult banking tools, or dislike the idea of coordinating money through a child-focused product. The free listing is attractive, but the possible in-app purchase range deserves attention, and the household still needs to decide how much independence is appropriate.
Overall, Till is most convincing when treated as a conversation tool with a card attached. It can help a child move from asking for cash to making small, visible decisions, while giving adults a practical role in the learning process. My recommendation is to choose it for guided independence, not automatic financial supervision.
FAQ
What is Till: Debit Card for Kids, and how does it work?
Till is a family-focused debit card and money management app designed to help children learn about spending, saving, and budgeting under parental supervision. Parents typically create and manage the account, add funds, and monitor activity, while children use their card for approved purchases. Availability, account features, and card controls may vary depending on the country and current Till policies.
Is Till safe for children to use?
Till is designed with parental oversight in mind, giving adults tools to manage a child’s spending and review transactions. Before downloading, parents should check the available security controls, notification settings, card-freezing options, and privacy policy. As with any payment product, children should be taught never to share their card number, PIN, passwords, or verification codes with anyone.
Are there fees for using Till: Debit Card for Kids?
The cost of using Till may depend on the selected plan, card type, funding method, delivery options, and other account services. Some features may be included while others could involve recurring or one-time charges. Because pricing can change, parents should review the latest fee schedule in the app or on Till’s official website before opening an account or ordering a physical card.
Can parents control how their child spends money with Till?
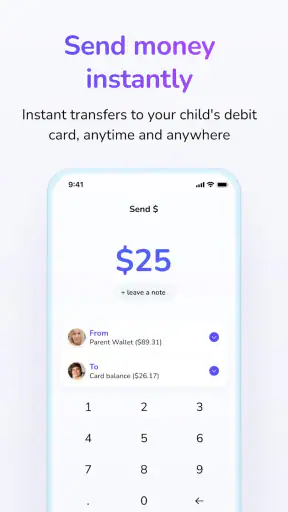
Till is intended to give parents visibility and control over a child’s finances, although the exact tools may differ by account and region. Parents may be able to add money, review transactions, receive spending notifications, and manage or restrict card usage. It is important to explore the current parental controls during setup and explain spending limits clearly to the child.
What age is Till suitable for, and what does a child need to sign up?
Till is aimed at families who want to introduce children to responsible money management, but eligibility requirements may depend on the child’s age, the parent or guardian’s location, and applicable financial regulations. A parent or legal guardian will generally need to create or approve the account and provide identification or personal details. Check Till’s current terms for exact age and verification requirements.


